
Ultra Low Payments, More Borrowing Power
A Flexible HELOC Program
Since the COVID-19 pandemic, home prices across the United States have risen substantially, leaving many homeowners with more equity in their homes. They can use the funds to pay off existing debt, cover their children’s education expenses, support their business, or supplement their retirement income.
Even with substantial home equity, however, qualifying for a cash-out loan can be difficult. Traditional home equity loans place significant weight on debt-to-income ratio (DTI) and income documentation. Self-employed borrowers, commission-based earners, and retirees whose income varies may face challenges during the approval process.
This HELOC program offers another option. It considers your home equity, credit, income, assets, and overall financial situation, while offering a choice of monthly payment plans. It may be worth exploring if you have equity in your home but have found it difficult to qualify under traditional lending guidelines.
This program may be helpful for self-employed homeowners who need business funds, those struggling with their current monthly mortgage payment, or retirees who want a monthly payment that better fits their retirement income.
This home equity line of credit (HELOC) allows borrowers to defer interest payments. By tapping into their home equity, they may be able to lower their required monthly payment compared with traditional loan products. A lower required payment may also help them qualify for a larger credit line, subject to underwriting.
Approval and the available credit limit depend on the home’s value, existing loans, credit, age, and other underwriting requirements.
You can explore your options with a free, no-obligation prequalification.
Ultra Low Payments
This HELOC (Home Equity Line of Credit) program offers flexible options for lowering your minimum monthly mortgage payment. Depending on eligibility, you can choose a payment plan from 1% to 5%. By deferring a portion of the interest, you may be able to lower your monthly payment. You can also pay more than the minimum at any time without a prepayment penalty.
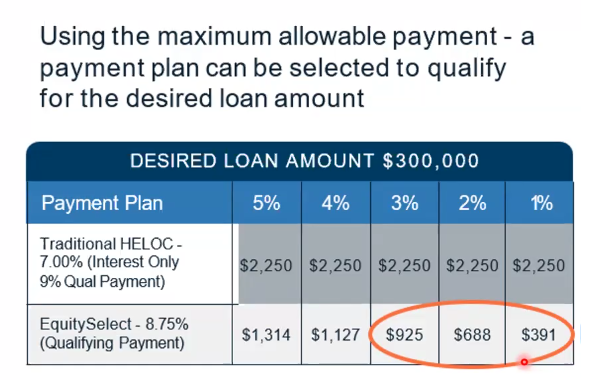
For example, on a $300,000 loan at an 8.75% interest rate,
the estimated minimum monthly payment is $391 with the 1% plan, $688 with the 2% plan, $925 with the 3% plan, $1,127 with the 4% plan, or $1,314 with the 5% plan.
Available payment plans vary by age:
- Under 50: 5% plan
- Ages 50–54: 3%–5% plans
- Age 55 and older: 1%–5% plans
The image below compares these payments with the monthly interest-only payment on a traditional HELOC at a 7% interest rate.
More Borrowing Power
With a traditional HELOC, you may have substantial home equity but still be unable to borrow the amount you want because the monthly payment is too high to meet lending requirements.
This program offers lower minimum monthly payment options, which may allow you to qualify for a larger loan using the same home equity. A lower qualifying payment may reduce the monthly debt amount used in the debt-to-income (DTI) calculation and increase the amount you may be eligible to borrow. Your actual loan limit will depend on the results of your individual application and underwriting review.
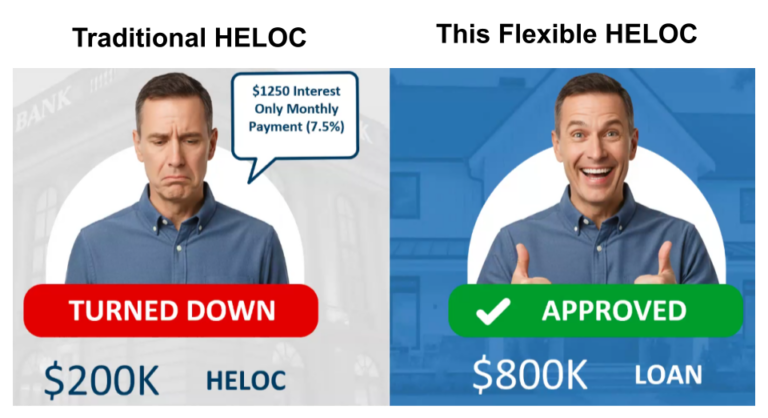
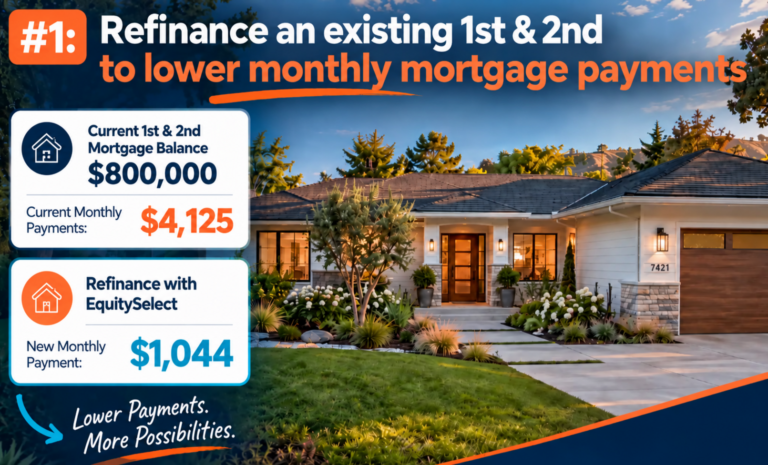
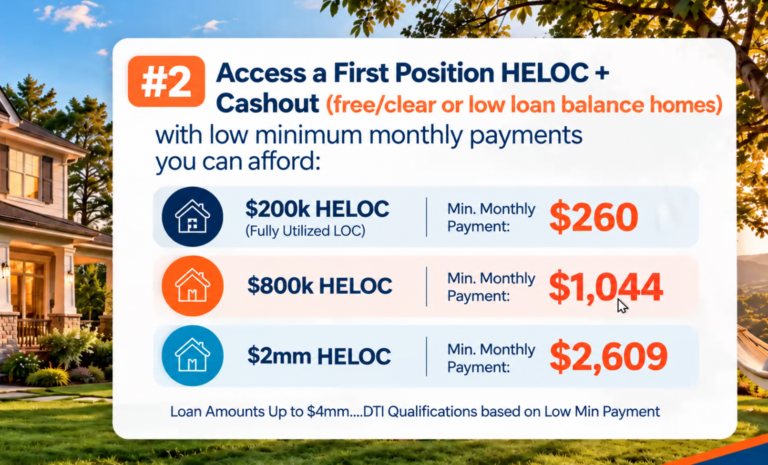
Illustrative example only; actual rates and payments may vary.
Low Monthly Payment Options:
Choose an age-based 1%–5% payment plan with a deferred-interest HELOC
No Prepayment Penalty
Pay more than the minimum at any time without a penalty
Interest Rate & Loan Term
SOFR rate + margin
Example: 3.87% + 5.99% = 9.86%
Loan term: 40 years
First-lien HELOC
- Up to $4,000,000
- Draw period: 7 years
Second-lien HELOC
- Up to $2,000,000
- Draw period: 5 years
No Recast
The monthly payment is not recast during the 40-year loan term
Protected LOC Balance
Deferred interest is added to the loan balance, but it does not reduce your available credit line
- Property requirement: An owner-occupied primary residence with substantial home equity.
- Credit score: 650 or higher
- Borrower eligibility: U.S. citizens or permanent residents
- Income documentation (Full Doc): W-2s or tax returns for the past two years
- Age-based payment plans: Borrowers under 50 may use the 5% plan; ages 50–54 may choose a 3%–5% plan; and borrowers 55 or older may choose a 1%–5% plan.
- If your monthly payment is less than the interest accrued, the unpaid interest is added to your loan balance. The remaining balance must be repaid when the loan reaches maturity or when you sell or refinance the home.
- Your selected minimum payment plan remains in effect throughout the 40-year loan term. You may pay more than the minimum each month, including the full amount of accrued interest or additional principal.
- First- or second-lien option: Pay off your existing mortgage and obtain a first-lien HELOC, or keep your existing mortgage and obtain a second-lien HELOC
- Initial draw requirement: Draw at least 50% of the credit line for a first-lien HELOC or 60% for a second-lien HELOC at closing. You may repay funds you do not need afterward.
- Borrowers age 62 or older: For first-lien loans only, eligible assets and an available line of credit (LOC) may be considered as income.
- Co-signers: A co-signer may be added to help meet debt-to-income (DTI) requirements.
- Loan-to-value ratio (LTV): Higher LTVs may be available at older ages, which may benefit retirees. 65% for 1st and 75% for 2nd lien.
- Non-recourse: In the event of default, the lender’s claim is limited to the home securing the loan, rather than the borrower’s other assets or income.
- Consultation and prequalification: Free
- Estimated loan process: Approximately one month
- Currently available state: AZ, CA, CO, CT, FL, GA, HI, ID, IL, MI, NC, NJ, NV, OH, OR, SC, TN, UT, VA
Who May Benefit from This Program?
Homeowners Who Need Access to More Cash
Your home equity may have grown as property values increased, but traditional HELOC income requirements may limit how much you can borrow.
Homeowners Struggling with Current Mortgage Payments
Refinancing an existing first mortgage, or both first and second mortgages, may help lower your monthly payment.
Self-Employed and Commission-Based Borrowers
If your business or commission income varies from month to month, a lower minimum payment may help you manage your cash flow.
Retirees with Assets but Limited Monthly Income
You may have substantial savings, investments, or other assets but find it difficult to meet a traditional HELOC’s income requirements after retirement.
Borrowers Declined for a Traditional HELOC or Approved for Too Little
Even with good credit and substantial home equity, income, DTI, or monthly payment requirements may prevent you from qualifying for the amount you need.
Homeowners Who Want More Flexible Monthly Payments
If your income varies or you need to manage cash flow, a lower minimum payment option may give you more flexibility.
Milestone Point Inc. In partnership with Loan Factory Inc. (NMLS #320841)
Licensed Mortgage Loan Officer: Terry Kwon (NMLS #2620208)
Residential Mortgage Licensed: AL, CA, CO, GA, IL, ME, NJ, NV, OH, PA, TX, VA, WA
Contact: (631) 624-4480
Email: terry@milestonepointinc.com
Milestone Point, Inc: 200 Garden City Plaza, Suite 215, Garden City, NY 11530
Loan Factory: 2195 Tully Road. San Jose, CA 95122
Disclaimer:
Loan approval is not guaranteed. Approval is subject to credit, income, assets, and other underwriting criteria.
Rates and terms are subject to change without notice.
Milestone Point Inc. partners with Loan Factory Inc. to provide access to multiple mortgage products.
All mortgage programs are offered through licensed mortgage brokers/loan officers registered with the NMLS.